
The tokenised fund conversation in Singapore has moved past the question of whether blockchain can support regulated investment products. The more pressing question is what happens when tokenised funds can settle against tokenised money across borders, around the clock, without correspondent banking friction. The answer is being assembled piece by piece in Singapore’s financial infrastructure.
The Settlement Stack: CBDC and Stablecoins in Parallel
MAS has been explicit about its endgame: a trusted digital money ecosystem where different forms of high-quality settlement assets support domestic and cross-border transactions while preserving safety and settlement finality . The wholesale SGD CBDC test network, operational since 2025, settled interbank lending among Singapore’s three largest local banks. The next step—settling tokenised MAS Bills with wholesale CBDC—brings tokenised government securities and tokenised central bank liabilities onto the same infrastructure .
Simultaneously, the Single-Currency Stablecoin framework creates a regulated private settlement asset. The requirements are substantive: 100% reserve backing, minimum capital of S$1 million or half of annual operating expenses, monthly external audits, and redemption at par . Only a handful of issuers have received full SCS approval, a deliberate constraint that prioritises trust over speed.
For tokenised fund managers, this dual-track approach matters because cross-border fund distribution requires a settlement asset that counterparties in different jurisdictions will accept. A tokenised fund denominated in USD and settled in a regulated stablecoin can bypass the multi-day delays of traditional correspondent banking. A tokenised fund settled in wholesale CBDC offers the ultimate credit risk profile: central bank money.
The Interoperability Challenge
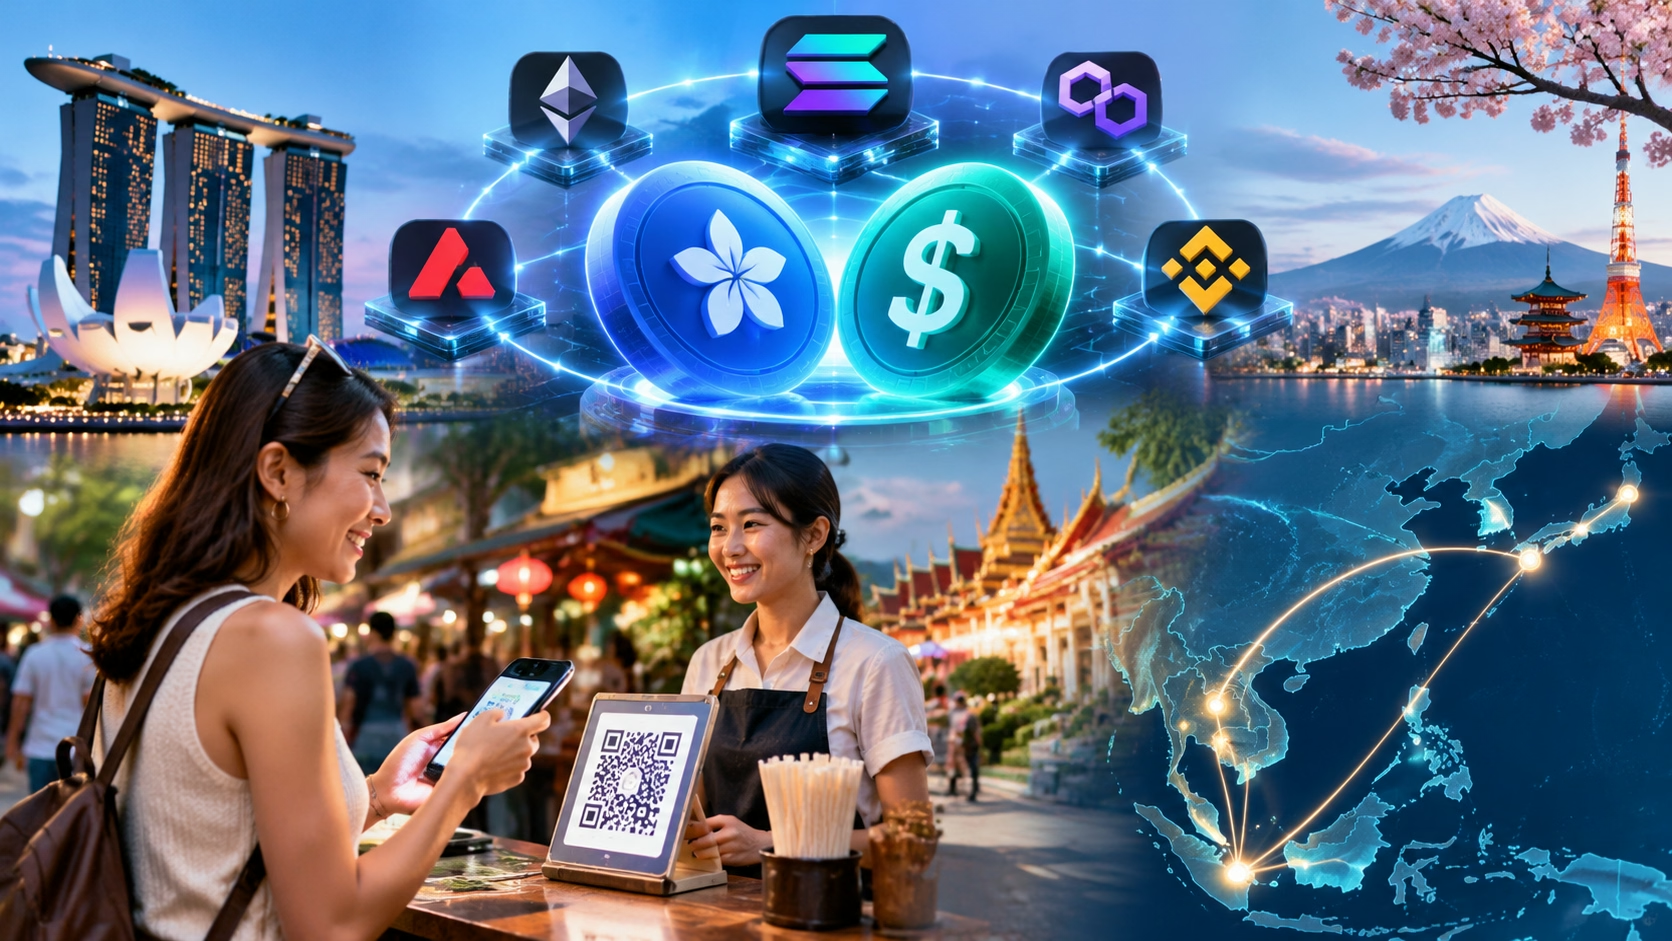
Project Guardian’s participants have tested atomic settlement, permissioned DeFi protocols, and cross-ledger interoperability across multiple currency pairs and asset classes . HSBC’s Orion platform has issued approximately US$2.5 billion in tokenised bonds as of April 2026, with integration for on-chain settlement against USDC, XSGD, and other digital currencies . UOB has led cross-border tokenisation experiments with Thailand, Malaysia, Vietnam, and the Philippines, positioning Singapore as the ASEAN hub for tokenised asset distribution .
The remaining obstacle is not technology but legal recognition. A tokenised fund unit issued in Singapore and traded on a licensed platform may still face uncertainty when the investor is in another jurisdiction with different securities law treatment. Singapore’s functional regulation framework addresses this domestically, but cross-border mutual recognition of tokenised securities remains a work in progress.
What Fund Managers Should Watch
The practical implication for asset managers evaluating Singapore as a tokenisation base is that the infrastructure is real but the distribution network is still forming. The VCC structure, the double tax agreement network spanning over 80 countries, and the Project Guardian ecosystem provide a credible foundation . But tokenisation does not automatically create liquidity. As one industry participant cautioned, the sector must avoid “tokenising for the sake of tokenising” . The funds that succeed will be those where the token delivers measurable operational or distribution advantage—not those that treat blockchain as a marketing label.

Leave a Reply