
The Classroom Has Moved to the Feed
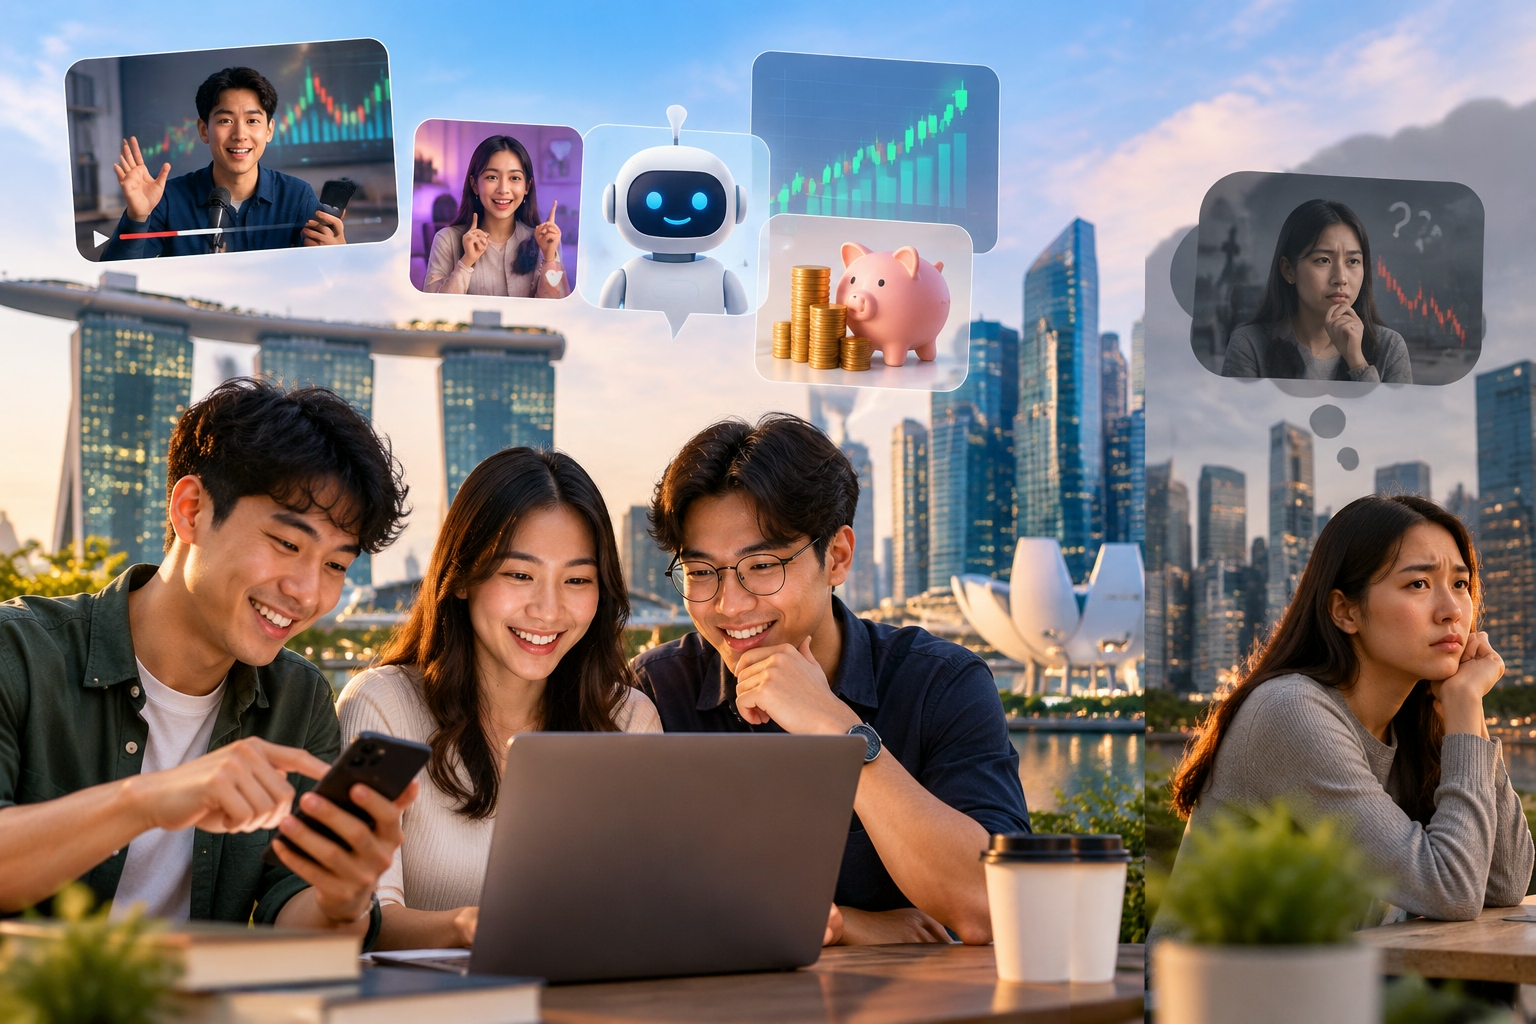
A decade ago, a Singaporean looking to learn about investing might have turned to a bank branch, a newspaper column, or a formal course. Today, the primary sources of investment education are YouTube, TikTok, and Instagram. The Everyday Investor Report 2026 found that 65% of young investors make decisions independently, and social media platforms have become their default classroom. This shift is not merely about where information is consumed—it is about who controls the narrative.
The implication is significant. When investment education happens on algorithmic platforms, the content that reaches a viewer is shaped by engagement metrics, not educational quality. A 30-second video about options trading can accumulate millions of views while a sober explanation of compound interest languishes. This creates a literacy asymmetry: investors may feel informed without actually understanding risk-adjusted returns, diversification, or the difference between investing and speculating.
AI Enters the Advisor’s Chair
Into this environment steps artificial intelligence. The same report found that AI chatbots are already the third most-used investing tool among young Singaporeans, with 26% using them to understand financial concepts or compare products. The UOB ASEAN Consumer Sentiment Study 2026, which surveyed 5,000 consumers across five Southeast Asian countries, found that Singaporeans use AI mostly to understand financial information (36%) and compare banking products (33%). Some use AI to make investment decisions (31%) or to prepare questions for human advisors (22%).
The appeal is obvious. An AI chatbot is available at 2 a.m., does not charge a fee, and can explain complex concepts in plain language. But the limitations are equally real. AI tools do not hold a fiduciary duty. They cannot assess whether an investment aligns with a user’s specific risk tolerance, time horizon, or life circumstances. They can democratize access to information, but they cannot replace judgment.
The Trust Deficit: Humans Still Win on Confidence
Despite the convenience of AI, Singaporeans remain more confident in human guidance. The UOB study found that 76% believe their primary bank will act in their best financial interest, and 70% feel the same about a human financial advisor or wealth manager. Only 57% believe AI-powered tools will act in their best interest. This trust gap suggests that AI is being used as a supplement, not a substitute—a tool for preparation and understanding, not for final decisions.
This pattern aligns with broader financial literacy best practice. Technology can reduce friction and lower the cost of access, but it cannot replace the accountability that comes from a human relationship. The most effective model may be a hybrid: AI for initial education and product comparison, followed by human consultation for personalized advice.
The Literacy Gap That Technology Alone Cannot Close
Here is the uncomfortable reality: if AI and social media were sufficient for financial literacy, the 33% of young Singaporeans who have never invested would have already entered the market. Their barriers—fear of losing money and not knowing where to start—are not information deficits that a better YouTube video can solve. They are confidence deficits, and confidence comes from structured learning, practice, and support.
Singapore’s institutional infrastructure already addresses this. MoneySense and the Institute for Financial Literacy provide free, unbiased, and structured education programmes. The CPFIS Self-Awareness Questionnaire enforces a baseline of understanding before investment. The question is whether these institutional resources can compete with the speed and appeal of a TikTok clip. The answer likely lies not in choosing between them, but in integrating them—making formal education as accessible and engaging as the platforms that currently dominate attention.

Leave a Reply